- Home
- Buying a Used Sailboat
- Yacht Insurance
Do I Need Boat Insurance? A Sailor's Guide to Cover, Premiums & Claims
Key Takeaways: Do you need yacht insurance? In a word, yes. It's a critical safety net that protects your financial investment and shields you from legal and operational headaches. From covering accidental collisions with other vessels to providing a lifeline during a hurricane or even an unexpected fire, the right policy ensures you're prepared for the worst while you enjoy the best of life on the water.
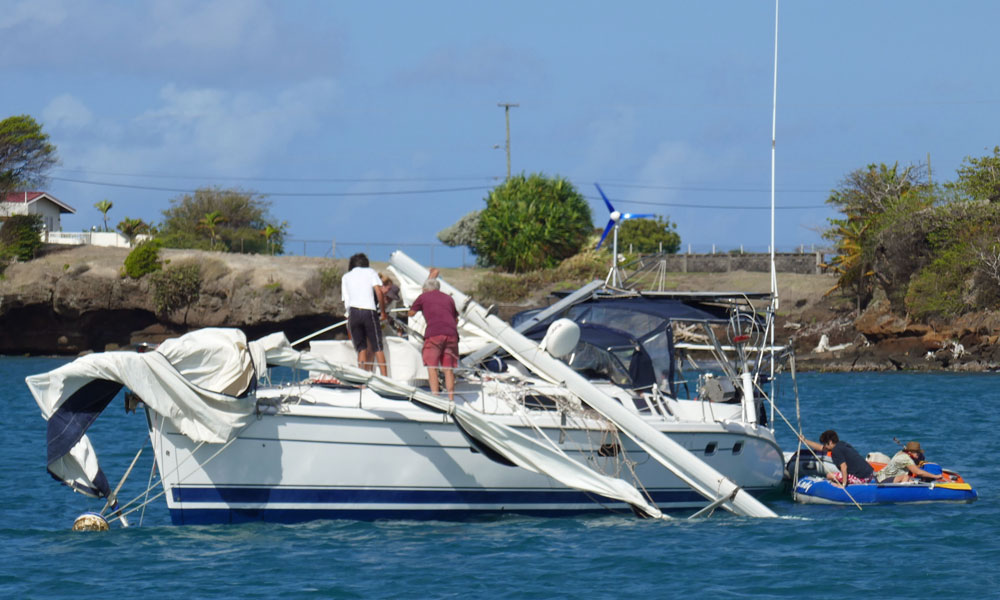 The failure of a single fitting can cause the loss of the entire rig...
Table of Contents
Why Bother with Yacht Insurance?
It's a fair question. The upfront cost of boat insurance isn’t exactly pocket change, and when you’re thinking about the thousands you've already spent on your vessel, it can feel like a heavy extra. After all, if some countries don’t even legally require it, is it really a good use of your money?
As a long-distance sailor, I’ve seen first-hand what can happen when things go wrong. From a dismasted yacht in the Caribbean to a wreck in Prickly Bay after a broken mooring, I can tell you that an unexpected incident can turn your dream into a financial nightmare in a heartbeat. Protecting your vessel and your wallet just makes good sense, whatever your cruising ambitions.
Let's look at a few reasons why you should never go without proper cover.
Protecting Your Investment & Your Wallet
Your boat is more than just a toy; it’s a significant investment of both capital and dreams. Just as you’d insure your home or car, a quality insurance policy is the best way to protect that investment. Without it, a fire, a theft, or a sudden sinking could leave you unable to repair or even replace your vessel.
Beyond the cost of your own boat, an accident could cause serious damage to another, far more expensive vessel. A collision in a crowded anchorage, for instance, could land you with a legal claim for thousands of pounds in repairs to someone else's yacht. This is where your third-party liability coverage kicks in, safeguarding you from ruinous legal fees and claims.
If you want extra peace of mind when your boat is left unattended, a remote monitoring system can help reduce risk. For details and exclusive reader discounts see Sentinel Marine Monitoring.
Operational Restrictions & International Requirements
If you're a sailor who likes to go places, you'll find that not having the right insurance can limit your freedom. Most marinas, storage yards, and even local moorings won't accept your vessel without proof of a minimum level of third-party cover.
And for those of us who venture further afield, it’s a non-negotiable. Whether you’re clearing customs in the Canaries or checking in with immigration in the Caribbean, officials will almost certainly want to see a valid insurance certificate. It’s an easy way to avoid an unexpected regulatory nightmare.
Beyond the Basics: Modern Coverage & Innovations
Today’s insurance policies have evolved far beyond basic accident coverage. Modern policies can now reflect how we actually sail, with some companies offering parametric and telematics-driven policies. For example, if your boat has a state-of-the-art tracking system or a weather alert monitor, your safe sailing habits and use of technology might even earn you a discount. This isn't just futuristic talk; it's a real trend that rewards vigilance and modern technology.
As environmental concerns rise, so too has the need for enhanced environmental and pollution liability coverage. Imagine having protection that not only covers physical damage but also tackles cleanup costs and legal fees if your vessel accidentally pollutes pristine waters. It's an increasingly important layer of security, especially if you navigate ecologically sensitive areas.
For those sharing the deck with crew or chartering their vessel, modern policies often extend to include crew, charter, and personal accident cover. That way, whether you're hosting guests for a quick day trip or setting sail with a dedicated crew for an ocean passage, everyone on board is protected from mishaps and unexpected medical emergencies.
| Standard Risks | Special Risks & Modern Additions |
|---|---|
| Accidental damage to hull, sails & machinery | Hurricane & local hazard cover (e.g., Caribbean) |
| Fire, frost & theft | Piracy & international waters cover |
| Collisions, sinking & grounding | Coverage for modern technological add-ons |
| Launching & hauling out | Environmental & pollution liability |
| Coverage for tenders, outboard motors & trailers | Crew, charter & personal accident cover |
Understanding Premiums, Limits & the Claims Process
When you're trying to find a policy, getting a handle on how premiums are calculated, what your coverage limits are, and how the claims process works is crucial.
Your premium is influenced by many factors: your boat's age, size, and where you sail it. Where you keep it in the off-season, and your past claims history also play a big part. Interestingly, investing in quality safety equipment—like an advanced monitoring system—can sometimes lead to a lower premium, as it demonstrates you're a responsible boat owner.
It's also essential to know exactly how much the insurer will pay out in a claim and what your deductible (or 'excess') will be. Don't be afraid to ask for real-world examples to understand what a "reasonable" deductible looks like.
Beyond physical damage, liability coverage should also extend to passenger injuries, legal defence costs, and scenarios specific to charter use. A good insurer will be happy to explain their processes. After all, when you're in the middle of a stressful incident, knowing the step-by-step claims process can be a real lifesaver.
Vessel Valuation & Your Insurance Policy
Understanding how your yacht is valued is crucial, as it directly impacts your insurance payout in the event of a total loss. When taking out a policy, you will generally be faced with two types of valuation: Agreed Value and Actual Cash Value.
- Agreed Value is a fixed amount agreed upon by you and your insurer when the policy is initiated. In the case of a total loss, this is the amount you will be paid. This type of policy is a good option for owners of classic, custom or well-maintained older vessels, as it prevents depreciation from reducing the payout.
- Actual Cash Value (ACV), on the other hand, factors in depreciation. If your vessel is a total loss, the insurer will pay out the market value of the boat at the time of the claim. While this type of policy often has a lower premium, the payout will be lower than the original insured value, as it accounts for wear and tear.
To establish the correct valuation, particularly for older or high-value yachts, a condition and valuation survey by a certified marine surveyor is often required. This independent report assesses the vessel's current state and worth, providing a fair and accurate basis for your insurance coverage.
Marine Salvage & Wreck Removal
The legal and financial distinction between marine salvage and wreck removal is a key consideration for any yacht owner. It determines who pays what costs in a disaster.
Marine salvage is the act of rescuing a vessel or its cargo from peril at sea. It operates on a "no cure, no pay" principle, meaning the salvor is only rewarded if the rescue is successful. The amount of the award is typically based on the value of the property saved. These costs are generally covered by your Hull insurance.
In contrast, wreck removal refers to the clearing of a vessel that has been declared a constructive total loss. This is done to remove an obstruction to navigation or to mitigate environmental damage. The financial responsibility for wreck removal falls under your Protection & Indemnity (P&I) insurance.
This distinction is important because a salvage operation can seamlessly become a wreck removal, with a significant shift in financial responsibility. It is therefore vital to have comprehensive policies that clearly define these two eventualities.
Finding a Yacht Insurance Company
Most sailboat owners find it pays to work with a specialist insurance broker rather than booking directly with a large provider. A good broker has an in-depth understanding of the marine insurance market and can negotiate on your behalf. They'll also be able to explain the fine print and help you compare quotes. And if you haven't bought your boat yet, remember that insurers will want a satisfactory survey before they issue a policy. Our guide, Buying a Used Sailboat: A Guide to Getting the Perfect Vessel & Sailing Away, explains how to find the right vessel and what the survey needs to cover.
An internet search will yield many options, but don't be lured solely by the cheapest quote. A quote from a reputable broker might seem more expensive initially, but a company with a proven track record of handling claims swiftly and fairly is worth its weight in gold. A broker who was able to manage a client's claim swiftly after Hurricane Ivan, for example, is demonstrating the kind of reliable support you'll need when trouble arises.
When you're assessing your options, you should always ask about:
- Risks Covered versus Exclusions: Understand exactly what's covered and what isn't. The exclusions are just as important as the inclusions.
- The Fine Print: Discuss any ambiguous clauses with your broker. What if you must abandon the boat mid-ocean? How does the policy handle a latent construction defect? Don't be afraid to ask about even the most unusual scenarios.
- Reputation & Claims Performance: It's not just about getting the quote; it's about knowing you have reliable support when you need it.
Summing Up
In a world where technology and innovation are changing everything, even yacht insurance is evolving. It's about combining traditional seamanship and wisdom with contemporary tools. For the best peace of mind, embrace modern innovations like telematics and enhanced environmental cover while staying grounded in the fundamentals: understand your policy's limits, what your premium factors are, and what the claims process looks like. Whether you're cruising locally or venturing into international waters, a well-tailored insurance policy is the one thing that will always keep you afloat, protecting your investment, your adventures, and your peace of mind.
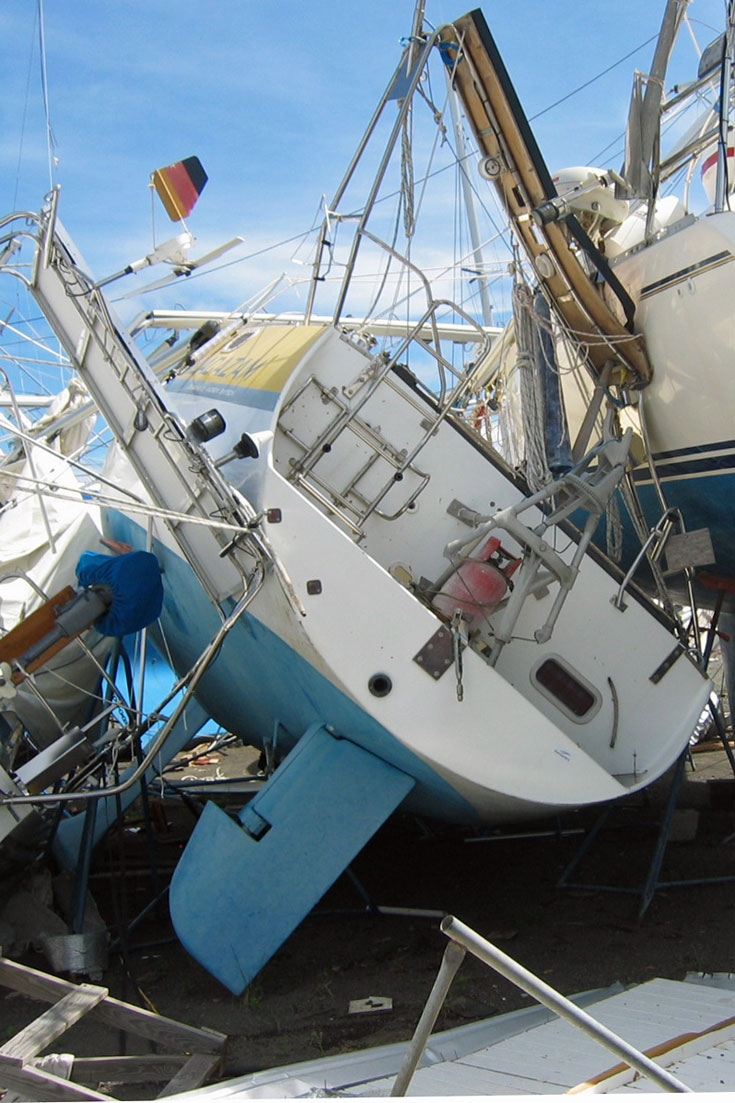 The devastating results of a category 5 hurricane...

This article was written by Dick McClary, RYA Yachtmaster and author of the RYA publications 'Offshore Sailing', member of The Yachting Journalists Association (YJA), erstwhile member of the Ocean Cruising Club (OCC) and owner/administrator of 'Liveaboard Sailboats for Sale'.

FAQs about Yacht Insurance
Q: Is boat insurance legally required in the UK?
Q: Is boat insurance legally required in the UK?
A: While there is no national legal requirement to have boat insurance in the UK, many marinas, harbours, and waterways authorities will insist on third-party liability insurance before you can use their facilities. It's a non-negotiable for most.
Q: Does my standard policy cover me for racing?
Q: Does my standard policy cover me for racing?
A: Standard policies generally don't provide adequate cover for racing. You'll need to check the policy wording carefully or opt for a specialist racing endorsement to ensure your rig and hull are protected.
Q: What is a 'latent defect', and is it covered by my insurance?
Q: What is a 'latent defect', and is it covered by my insurance?
A: A latent defect is a hidden fault in the boat's design or construction that isn't discoverable through a normal inspection. It's a common exclusion, so you must specifically check your policy's fine print to see if it's covered.
Q: Will my policy cover me if I lend my boat to a friend?
Q: Will my policy cover me if I lend my boat to a friend?
A: This is a key detail to clarify with your insurer. Some policies may have a 'named operator' clause, while others might cover any competent sailor you give permission to use the boat. Never assume your friend is covered without checking.
Q: What should I do immediately after an incident?
Q: What should I do immediately after an incident?
A: Your first priority is always safety. Once everyone is safe and secure, you should contact your insurer or broker immediately to report the incident. They can then guide you through the next steps, such as documenting the damage, arranging for surveys, or notifying the authorities.
Q: Does boat insurance cover personal belongings?
Q: Does boat insurance cover personal belongings?
A: Standard policies often include some coverage for personal effects, but this is usually limited. If you have expensive personal gear like electronics, cameras, or clothing, you should check with your insurer about increasing this coverage.
Recent Articles


-
Should I Buy a Boat? Four Questions to Answer Before You Commit
Oct 02, 26 04:40 AM
Thinking "Should I buy a boat?" This guide helps you decide, with key considerations from cost & maintenance to your personal sailing aspirations. -
Offshore Internet with Starlink: Hardware, Plans, and Setup Guidance
Oct 01, 26 01:15 PM
A clear, practical guide to choosing the right Starlink hardware and plan for offshore cruising. Learn what to buy, how to install it, and how to manage power afloat. -
Offshore Liferaft Guide: Choosing, Stowing and Servicing One
Oct 01, 26 06:28 AM
Choosing an offshore liferaft? Learn what ISO 9650 Group A means, where to stow it, how often to service it and what to pack in the grab bag.